Commercial Insurance Belfast & Northern Ireland
Commercial insurance in Belfast typically refers to combined packages that bring several covers — premises, liability, stock and business interruption — into a single policy tailored to a commercial operation. This page explains what commercial insurance can include, how it differs from a basic liability policy, and what to check before arranging cover.
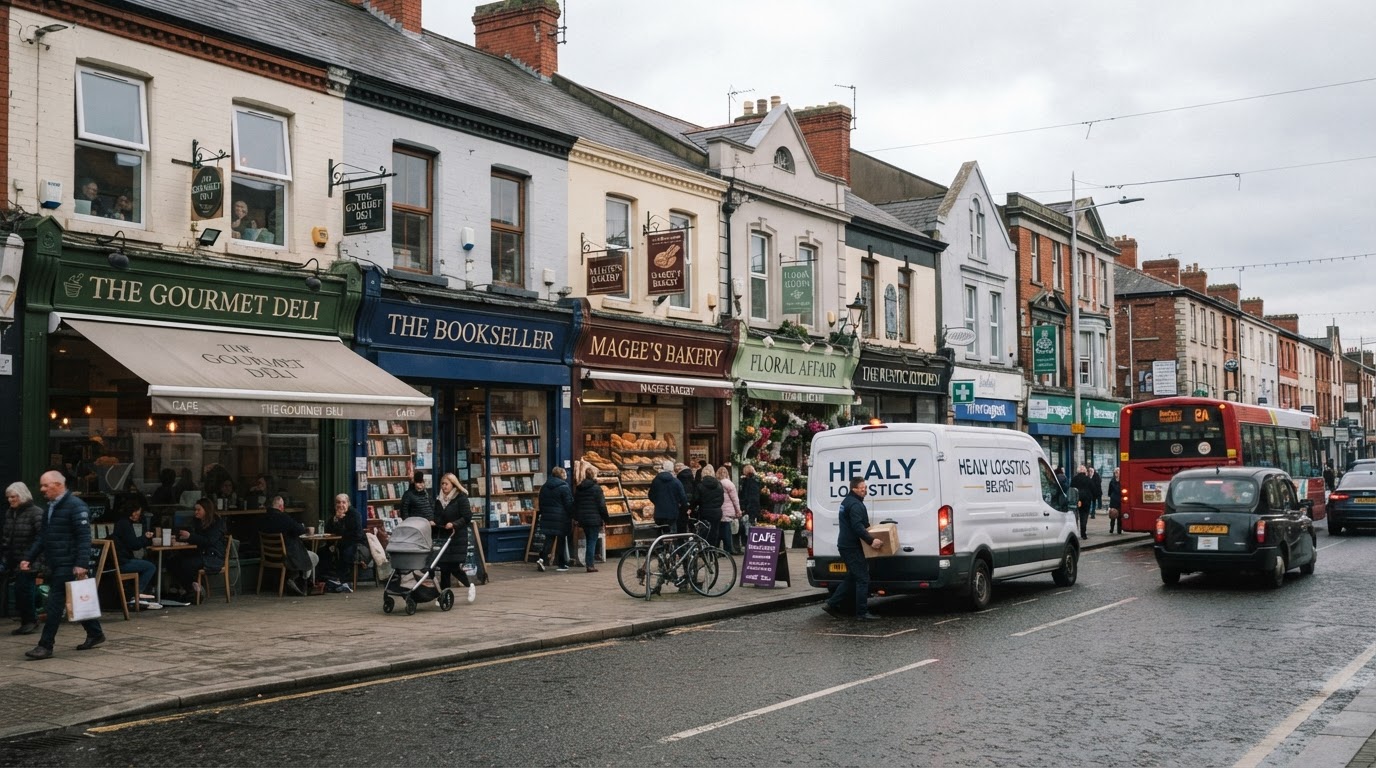
What commercial insurance can include
A commercial combined policy bundles several sections of cover so that a business can insure its premises, stock, liability and income together. The exact sections vary by insurer and business, but commonly include:
- Commercial buildings and contents
- Stock and goods in transit
- Business interruption following an insured event
- Public and employers' liability
- Money cover
- Cyber and crime cover where specifically added
The problem: 'commercial' means different things to different businesses
The word 'commercial' is used loosely, and two commercial policies can cover very different things. A shop may need stock and money cover; an office may need contents and business interruption; a manufacturer may need plant, stock and liability. Buying a 'commercial' policy without checking the sections can leave a business paying for cover it does not use, or missing cover it does need.
Another common issue is underinsurance on buildings and stock. If sums insured are set too low, a claim may be reduced under average or similar policy terms. Setting sums insured on the correct basis — rebuild cost for buildings, replacement cost for stock — matters more than many businesses realise.
Why commercial cover matters
A fire, flood, theft or liability claim can disrupt a commercial operation for months. Business interruption cover can help with lost income during the rebuild or recovery period, but only if the sum insured and indemnity period are set appropriately. Liability claims from customers or the public can be substantial, and the level of indemnity should reflect the business's exposure.
Premiums reflect the level of risk an insurer is taking on. Factors that commonly influence the cost of commercial insurance include the business type and activities, turnover and payroll, property values and stock levels, security and risk controls, and claims history. Each case is assessed on its own circumstances.
How to compare commercial insurance in Belfast
List your premises, stock, equipment, employees and activities before comparing. Check which sections each policy includes, the sums insured and excesses, the basis of business interruption cover (for example, gross profit or revenue), and any conditions on security, stock storage or health and safety. Confirm that all your business activities are declared and covered.
When you are ready, speak to an appropriately authorised insurer or insurance intermediary. You can check whether an insurer or insurance intermediary is authorised on the Financial Conduct Authority's Financial Services Register at register.fca.org.uk, and check a firm's permissions and any disciplinary history. Always confirm a provider is appropriately authorised before sharing detailed personal or business information or arranging cover.
ANSWER ENGINE OPTIMISATION (AEO)