Business Insurance for Sole Traders Belfast & Northern Ireland
Business Insurance for Sole Traders in Belfast and Northern Ireland refers to cover for a sole trader's business risks This page explains what business insurance for sole traders involves, what to check before arranging it, and how to approach an authorised insurer or broker in Belfast or across Northern Ireland.
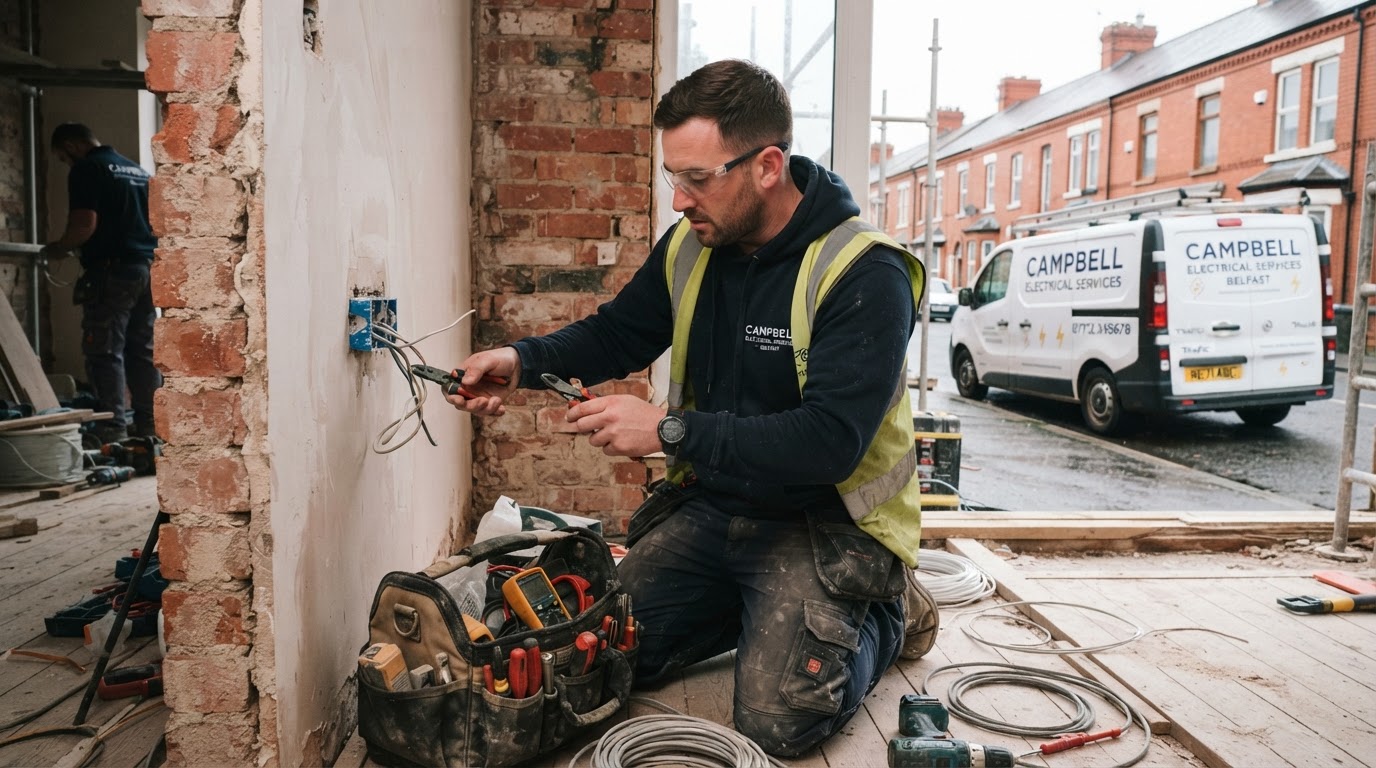
Understanding business insurance for sole traders in Belfast and Northern Ireland
Business Insurance for Sole Traders covers the business risks a sole trader faces — public liability, equipment, professional indemnity where relevant, and possibly stock — depending on the trade and activities. It is relevant to sole traders, and the right approach depends on the specific activities, premises, staff and contracts involved.
This page does not sell insurance, provide quotes or arrange cover. It explains what business insurance for sole traders involves, what to check, and how to approach an authorised insurer or broker before you arrange cover in Belfast or across Northern Ireland.
The problem: a common problem is a sole trader assuming personal cover extends to business activities. a home or motor policy often excludes business use, and a sole trader who works at clients' premises may need public liability that a personal policy does not provide.
A common problem is a sole trader assuming personal cover extends to business activities. A home or motor policy often excludes business use, and a sole trader who works at clients' premises may need public liability that a personal policy does not provide.
Another issue is that business insurance for sole traders varies by circumstance. The cover or service that suits one sole traders may not suit another, because the risks depend on the specific activities, scale and location. Understanding what you actually need — rather than assuming a generic package will do — is the first step to arranging cover that fits.
Why business insurance for sole traders matters
A sole trader's personal and business assets are not legally separate, so a liability claim or a loss of equipment can affect the individual directly. The right business cover protects the sole trader's livelihood, and public liability is often the most important cover for a sole trader who works with the public or at clients' premises.
It is also worth understanding what is typically included and excluded. The scope varies between providers, and some features may be optional add-ons rather than standard. Reading the exclusions, conditions and limits — not just the summary — is the only way to understand what the cover includes.
Premiums reflect the level of risk an insurer is taking on. Factors that commonly influence the cost include the trade and activities, the value of equipment and stock, whether you work at clients' premises, claims history. Each case is assessed on its own circumstances, so premiums vary between sole traders and providers.
How to compare business insurance for sole traders in Belfast
Before comparing, list your activities, assets and circumstances. Then check: whether your personal cover extends to business use; whether you need public liability for working with the public or at clients' premises; the value of your business equipment; whether your trade needs professional indemnity. Confirm that all your activities are declared and covered. When you are ready, speak to an appropriately authorised insurer or insurance intermediary. You can check whether an insurer or insurance intermediary is authorised on the Financial Conduct Authority's Financial Services Register at register.fca.org.uk, and check a firm's permissions and any disciplinary history. Always confirm a provider is appropriately authorised before sharing detailed personal or business information or arranging cover.
ANSWER ENGINE OPTIMISATION (AEO)